Agreed value classic car insurance sets a vehicle’s insured value with the insurer before a covered total loss. It can be especially useful when a collector car’s rarity, condition, or restoration history is not reflected by routine used-car pricing.
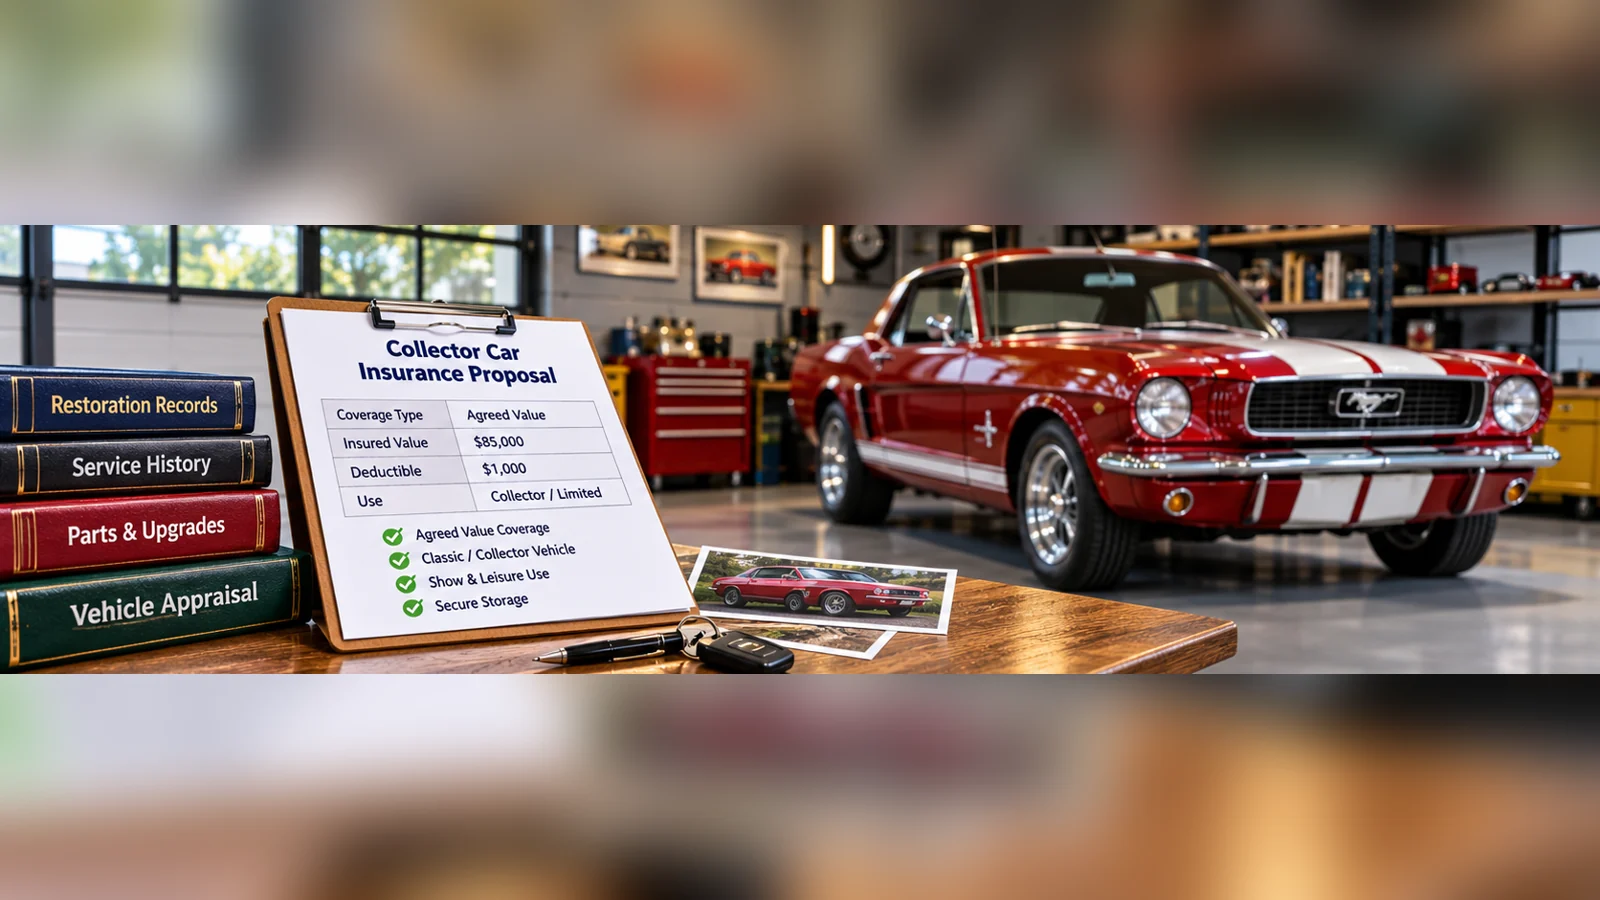
To obtain this coverage, document the car, confirm collector-policy eligibility, and review the actual settlement wording. A dollar amount appearing on a quote does not by itself establish agreed-value coverage. Ask the insurer to identify the policy provision that supports the proposed payment basis.
Understand the valuation terms first
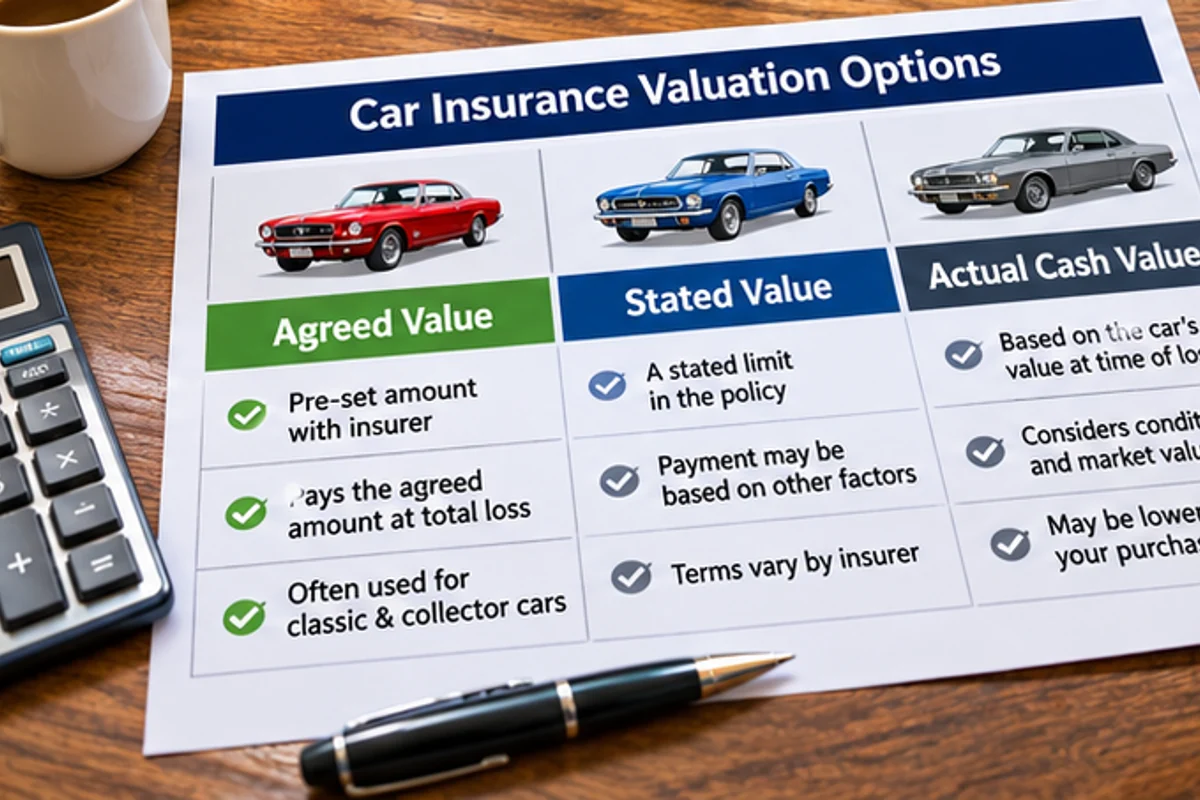
Agreed value
Under an agreed-value arrangement, the owner and insurer establish an accepted insured amount in advance. Some insurers use a branded term such as “Guaranteed Value.” Any payment remains subject to the policy’s covered-loss requirements, exclusions, deductible, and other applicable adjustments.
Read how retained salvage, taxes, fees, and deductibles are handled. Those details can affect the final payment even when the vehicle’s value was agreed beforehand. The valuation arrangement also does not turn an excluded event into a covered claim.
Stated value
A stated amount may set a limit while allowing another settlement calculation under the policy. Request the actual loss-settlement clause instead of relying on the terms “stated value” and “agreed value” being used interchangeably.
Ask what happens if the insurer’s assessed value is lower than the amount shown and whether repair cost or another measure can control the payment. Understanding that answer before a loss is more useful than discovering the distinction during a claim.
Actual cash value
Actual cash value generally concerns the vehicle’s value at the time of loss under the applicable policy rules. Condition and market evidence may matter, but the purchase price is not automatically the payment. For a valuable collector vehicle, ask whether that basis fits the protection you want.
Confirm that your car and use qualify
Collector insurers evaluate the vehicle and how it is used. An older car driven every day may not qualify for the same program as a weekend collectible. A newer limited-production car may raise a different eligibility question despite its age.
Some collector programs allow shows and occasional pleasure driving while restricting daily driving or commuting. Storage expectations also vary. Describe the actual use, parking arrangements, permitted drivers, routine errands, planned trips, and whether a regular-use vehicle is required.
Build a valuation file the insurer can evaluate
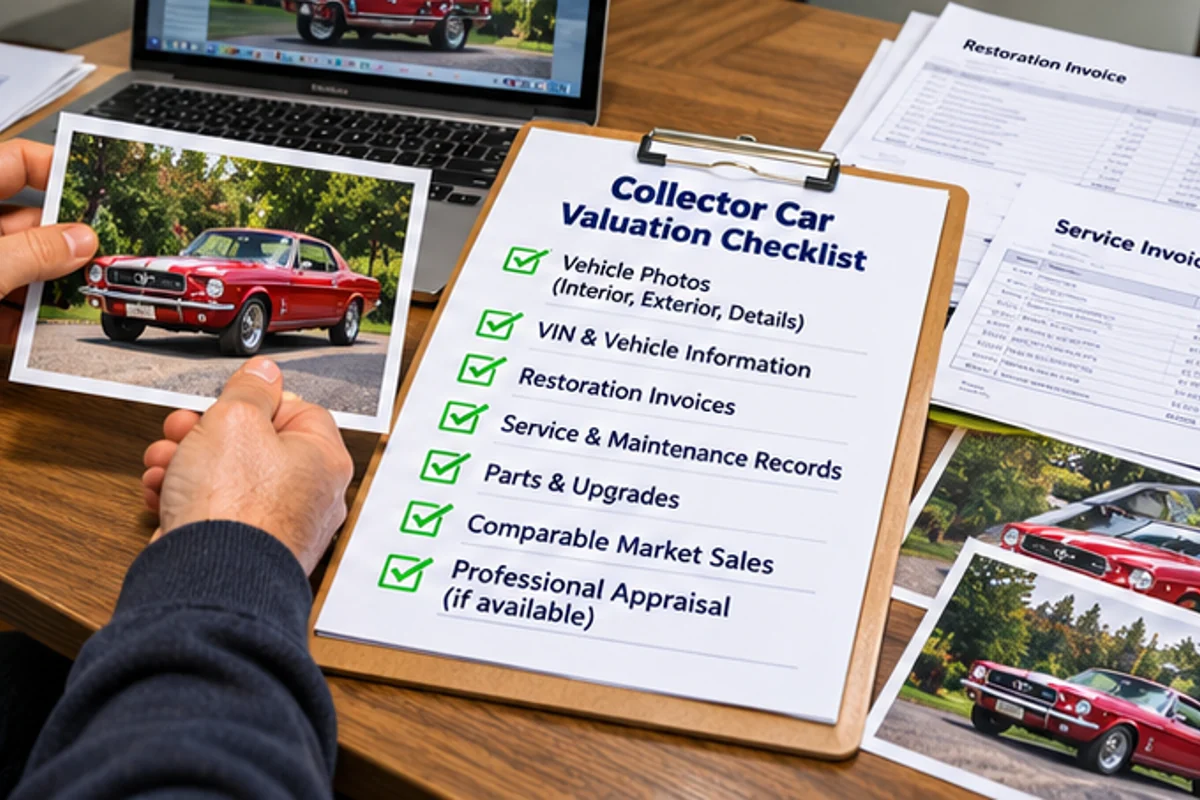
Start with the VIN, model year, mileage, ownership documents, and an accurate vehicle description. Photograph the exterior, interior, engine compartment, and notable details. Use current images and disclose defects rather than selecting only views that hide the condition.
Explain restoration work, modifications, originality, and documented provenance. Keep receipts organized by the work performed. Money spent on a project helps describe it, but total restoration expenditure does not automatically equal market value or the amount an insurer will accept.
Collect relevant valuation references or comparable completed sales where available. Note differences in condition and specification. An asking price for a substantially different car is weak support for the value you want assigned.
Ask whether an appraisal is required
Some insurers can assess submitted information without a formal appraisal; others may request one for a particular vehicle or value. Ask before hiring an appraiser and confirm which qualifications, report details, inspection dates, and valuation methods the insurer accepts.
Request comparable collector car insurance quotes
Use the same proposed vehicle value, drivers, address, and usage details for each application. Match liability limits and deductibles where possible. If a carrier changes the valuation or eligibility conditions, record that difference rather than comparing the premium alone.
Online applications can start the process, but unusual vehicles may need additional underwriting review. Ask whether the estimate has final acceptance and what remains outstanding. A completed form or saved proposal is not the same as active insurance.
Compare more than the agreed dollar amount
| Policy question | What to establish before buying |
|---|---|
| Settlement basis | The actual agreed-value clause and accepted amount |
| Deductible | What is subtracted from a qualifying claim |
| Retained salvage | Whether keeping the damaged car reduces payment |
| Permitted use | Accepted trips, drivers, mileage, and storage arrangements |
| Repair treatment | Parts, repair facilities, and approval requirements |
| Extra property | Limits for spare parts, tools, or equipment if included |
Ask how a partial repair differs from a covered total loss. An agreed amount does not promise a replacement vehicle after every dent. Repair authorization, parts availability, and policy terms still need review.
Know what a hypothetical settlement shows
Suppose a policy accepts an agreed amount of $60,000 and has an applicable $500 deductible. A covered total-loss calculation could begin at $59,500 before any other adjustments required by that contract. This is an arithmetic example, not a settlement promise.
If you want to retain the salvage, ask how that changes the result. Also review any outstanding loan and the lender’s required details. Agreed value is not automatically a guarantee that every financing obligation will be satisfied.
Discuss storage and activities needing separate attention
Tell the insurer about a restoration project, long-term storage, or a move to another garage. A car being worked on can have different needs from a finished vehicle driven to shows. Ask whether its current condition and location are accepted.
Track driving, timed events, or commercial hire need an explicit coverage discussion. Do not assume a collector road policy covers them because the car is performance-oriented. If a transporter will carry the vehicle, review insurance during pickup, transit, and delivery.
Keep the insured value current
Review the amount at renewal and after significant restoration or changes. Send updated records when required and request confirmation that a revised value has been accepted. A folder of new receipts does not amend the policy by itself.
Frequently asked questions
Can I choose any agreed value I want?
The insurer must accept the amount. Submit accurate records and supporting information, and ask what additional evidence is needed if the figure is questioned.
Does agreed value cover every kind of loss?
No. It establishes a valuation arrangement within the contract. Covered events, exclusions, duties, and limits still determine whether and how a claim is paid.
Is an appraisal always necessary?
Requirements vary by insurer and vehicle. Ask first so you obtain the right documentation without paying for an unnecessary or unacceptable report.
Can I commute with a collector policy?
Confirm permitted use before doing so. Some collector programs restrict daily driving or commuting even when occasional pleasure trips are accepted.
Sources and further reading
- Hagerty — Classic car coverage and Guaranteed Value conditions.
- Progressive — Agreed value and stated value insurance.
- Hagerty — U.S. collector vehicle eligibility guidelines.
USAutoInsuranceHub provides general educational information and is not an insurer, agency, broker, or claims representative. Coverage is governed by the policy contract and applicable law.
Previous and next articles
Related guides
 U.S. Car Insurance Guide: Coverage, Policy Comparison, and Claims Basics